Group Credit Exposure in B2B: How to Aggregate Risk Across Affiliated Buyers
Credit limits set buyer by buyer can hide a much larger exposure to one corporate group. Learn how to link affiliates, aggregate group credit exposure, and set limits.
Group Credit Exposure in B2B: How to Aggregate Risk Across Affiliated Buyers
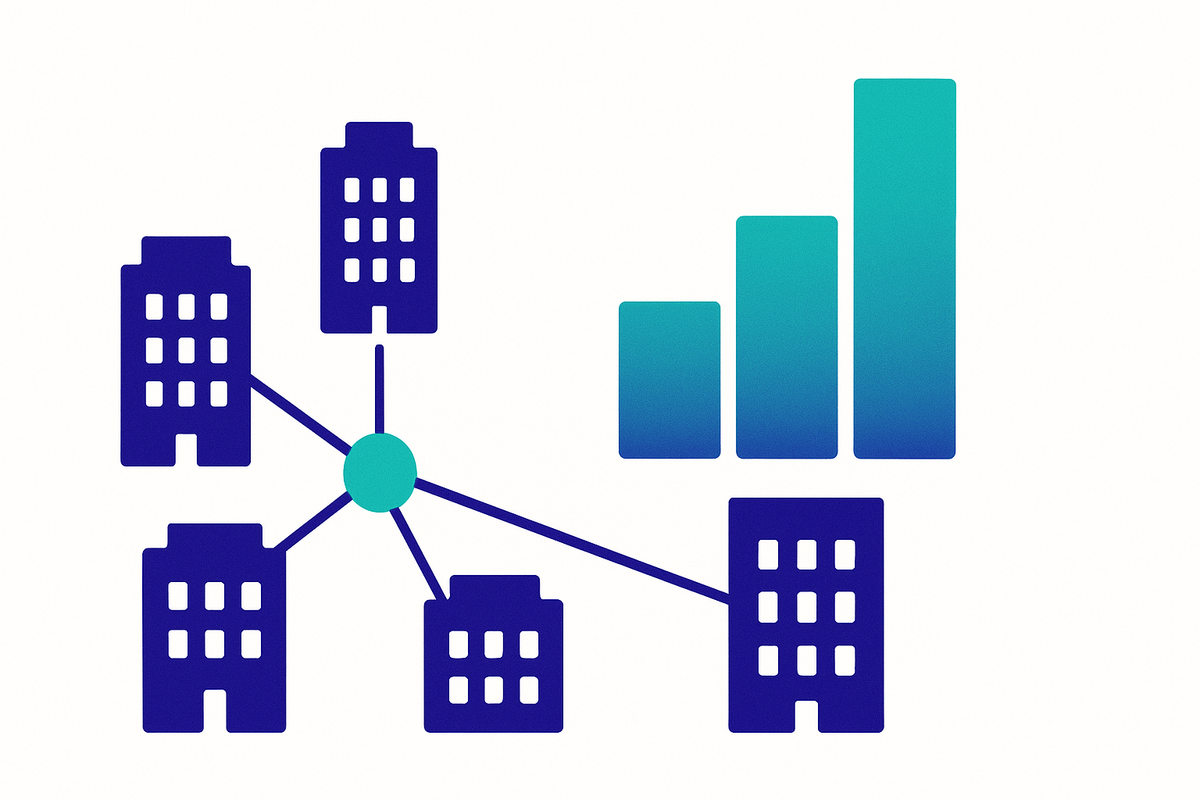
Most credit systems are built around a simple unit: one customer account, one credit limit. That works well when each customer is genuinely independent. It works badly when five "customers" in your ledger are really five legal entities controlled by the same parent, sharing the same treasury, the same management, and the same fate.
Group credit exposure is the total amount you are owed, or could be owed, by a set of buyers that are linked by ownership, control, or financial dependence. If you only look at each account separately, you can sit comfortably inside every individual limit while carrying a concentration to one corporate group that you would never have approved as a single line.
This guide explains why group exposure gets missed, how to identify affiliated buyers, how to aggregate exposure sensibly, and how to set limits and monitoring that reflect the real counterparty. It builds on our guides to customer concentration risk, setting B2B credit limits, and beneficial ownership verification.
What Is Group Credit Exposure?
Group credit exposure is your combined exposure to all members of a corporate or economic group. A "group" can mean several things:
- Parent and subsidiaries. A holding company with operating companies underneath it, often one per country, brand, or business line.
- Sister companies. Entities owned by the same shareholders but with no legal parent-child link between them.
- Franchise, buying group, or cooperative members. Independent legal entities that trade under one banner or purchase through a central arrangement.
- Economically dependent entities. Companies that are legally separate but rely on a single related party for most of their revenue, funding, or inventory.
The common thread is correlated failure. If the parent runs out of cash, its subsidiaries tend to run into trouble at the same time, whatever each balance sheet says. Treating them as independent credits overstates your diversification.
Why this is a real issue and not a theoretical one
Three structural features of B2B trade create the blind spot:
- Accounts are created by transaction, not by ownership. Each subsidiary, location, or purchasing office gets set up when it places an order. Nobody sits down to map the family tree.
- Legal entities are cheap to create. Groups legitimately organize by country, product line, or acquisition history. That is normal. It just means the ledger fragments the exposure.
- Credit decisions are made at account level. Limits are approved against the entity's own financials, and each approval looks reasonable in isolation.
The result is that no single decision is wrong, but the sum of them is.
How Group Exposure Gets Hidden
Group exposure is usually missed innocently rather than deliberately. Common ways it builds up:
- Multiple accounts from one acquisition. A buyer you already supply acquires another buyer you also supply. Both accounts stay open under their old names and old limits.
- Regional entities. A multinational's local subsidiaries each order under their own names, in different currencies, handled by different sales reps.
- Bill-to and ship-to confusion. Orders ship to one entity but are invoiced to another, and the paying entity is not the one you underwrote.
- Name variations. Slightly different spellings, abbreviations, or trading names mean the same buyer appears under multiple customer records.
- Intercompany payment arrangements. One entity pays invoices on behalf of others, so payment behavior on one account reflects the health of the whole group's treasury.
Sometimes the fragmentation is not innocent. Splitting activity across several entities is also a tactic used to stay under review thresholds. This is one reason why group mapping is a useful control against fraud as well as against ordinary concentration. Our article on bust-out fraud in B2B trade credit covers how coordinated entity networks can be used to inflate exposure quickly.
Group Credit Exposure and Buyer Risk Assessment
Group-level thinking changes what a good credit assessment looks like. Instead of asking only "can this entity pay?", you ask:
- Who ultimately controls this entity?
- Does the entity depend on a parent or affiliate for cash, guarantees, or revenue?
- What is my total exposure to everyone in that structure?
- If the weakest member of the group fails, what is the realistic impact on the others?
This is a natural extension of a proper buyer risk assessment. It also depends on the same raw material: reliable data on legal entity, ownership, and control.
Want to see who really stands behind a buyer? Check a buyer on BuyersIntelligence.ai - verify the entity, trace ownership, and see risk signals in one place. Free to start.
Step 1: Identify Which Buyers Are Connected
You cannot aggregate what you have not linked. Start with the information you already hold, then enrich it.
Sources inside your own business
- Customer master data. Look for shared addresses, phone numbers, tax or registration numbers, bank details, and contact email domains across accounts.
- Credit applications. Applications often disclose parent companies, affiliates, and principals. Capture these as structured fields rather than leaving them in PDFs. See our guide to building a B2B credit application that works.
- Payment data. If one entity regularly pays another entity's invoices, they are linked in practice even if the paperwork says otherwise.
- Sales and account management knowledge. Reps often know that two customers are "the same people". Make it easy for them to record that.
External sources
- Corporate registries. Registries in many jurisdictions show shareholders, directors, and registered addresses. Coverage and depth vary by country.
- Beneficial ownership information. Where available, ultimate beneficial owner records help connect entities that share an owner but not a parent. Our guide to beneficial ownership verification goes through this in detail.
- Commercial data providers. Many provide corporate family trees ("linkage") covering parents, subsidiaries, and branches.
- Public filings and annual reports. Listed groups usually disclose significant subsidiaries and related-party relationships.
Types of linkage to record
Not every link carries the same weight. Record the type, because it should affect how you aggregate:
| Link type | Example | Typical treatment |
|---|---|---|
| Majority ownership (over 50%) | Parent and wholly owned subsidiary | Aggregate fully |
| Common control | Same individual or family controls both | Aggregate fully |
| Minority ownership | A partial stake with no control | Review case by case |
| Guarantee relationship | Parent guarantees subsidiary debt | Aggregate on the guarantor |
| Economic dependence | One entity supplies most of another's revenue | Aggregate or review jointly |
| Shared management only | Same directors, no ownership link | Flag, investigate, may aggregate |
Step 2: Decide How to Aggregate Exposure
Once connected accounts are linked, you need rules for measuring the combined exposure.
What counts as exposure
Include more than the open invoice balance:
- Outstanding receivables across all linked accounts, including disputed amounts.
- Open orders and unbilled shipments that will become receivables.
- Contingent exposure, such as consignment stock or extended-dating arrangements.
- Pending credit increases that have been approved but not yet used.
Using only the current balance understates what you stand to lose if the group deteriorates quickly, because open orders convert into receivables fast.
Gross vs net aggregation
Some groups have accounts that owe you money and accounts where you owe them money, for example through rebates or returns. Be careful about netting. Unless your contract and local law clearly allow set-off across separate legal entities, treat exposure on a gross basis for credit purposes. Net exposure is a legal and accounting question that you should confirm with counsel rather than assume.
Currency and entity level
Group exposure often spans currencies. Convert to a single reporting currency at a consistent rate and track the effect of currency movement on the total, an issue we cover in our post on currency risk in B2B trade.
Step 3: Set Limits at the Group Level
The point of aggregating is to act on it. A workable structure uses two layers of limits:
- A group limit that caps total exposure to the whole linked set, based on the group's consolidated financial strength and your own risk appetite.
- Entity sub-limits within the group limit, based on each entity's own standing and, where relevant, whether it is covered by a parent guarantee.
How to size the group limit
Think about what determines how much you can safely lend to a group:
- Consolidated financial capacity. If consolidated accounts are available, use them as a starting point, then check how much of the group's strength sits in the specific entities you sell to.
- Structural subordination. Money and assets may sit in entities you are not dealing with. A strong parent does not make a weak subsidiary creditworthy unless the parent is legally standing behind it.
- Your own capacity to absorb a loss. Tie the cap to a share of your equity or annual revenue, in line with your credit policy.
- Quality of information. If you cannot see the full group structure, your limit should be more conservative than the financials alone would suggest.
Use guarantees to turn a loose link into a real one
If you are relying on a parent's strength to support a subsidiary's limit, get that support in writing. A parent guarantee or a personal guarantee from principals converts an informal expectation into an enforceable claim. Without it, the parent's balance sheet is comfort, not collateral.
Avoid the two common extremes
- Too loose: treating each entity as independent and approving each limit on its own.
- Too tight: cutting a whole group off the moment one affiliate has a problem, without checking whether the problem is contained.
The aim is proportionate response. Group-level thinking should make decisions better informed, not automatically more restrictive.
Step 4: Monitor the Group, Not Just the Account
Group risk changes when anything in the structure changes. Your monitoring should reflect that.
Signals worth watching across the whole group
- Payment behavior drift in any member, especially the entity that pays on behalf of the others.
- Ownership changes, including acquisitions, disposals, and restructurings. See our article on change of control credit risk.
- Distress at parent or affiliate level, such as covenant breaches, refinancing difficulty, or leadership departures. Our guide to spotting financial distress in B2B buyers lists the indicators.
- New entities appearing with shared contacts, addresses, or bank details.
- Legal events, including litigation, liens, or insolvency filings affecting any member.
Annual reviews miss most of this. Group structures change throughout the year, which is a core argument in our piece on continuous buyer monitoring.
Define group-level triggers
Write down in advance what happens when a signal appears. For example:
- A significant negative event at any group member triggers a review of the whole group limit.
- An insolvency filing at one member places the linked accounts on a heightened-review or credit hold pending analysis.
- A new acquisition by a customer triggers a check of whether the target is already in your ledger.
What Happens When a Group Member Fails
Group exposure matters most at the moment something goes wrong. A few mechanics are worth understanding before you need them.
- Legal separateness usually holds. In most jurisdictions, each entity is a separate legal person, and a creditor of one subsidiary cannot simply claim against the parent. That is the whole reason guarantees matter.
- Intercompany balances can complicate recovery. Groups often owe money internally, and insolvency practitioners may deal with those claims in ways that reduce what is available to outside creditors.
- Cash may be pooled. Group treasury arrangements can mean that one entity's bank account is swept to cover another's obligations, so a failure may spread faster than the legal structure suggests.
- Speed matters. Once one member files, shipments to the others should be reviewed immediately. Our guide on what to do when a B2B buyer files for bankruptcy covers the first steps.
None of this is legal advice. Insolvency law differs significantly across jurisdictions, and recovery options depend on your contracts, your security, and local rules.
A Practical Group Exposure Checklist
Use this as a starting point for your own process:
- Add structured fields for parent company, ultimate owner, and known affiliates to your credit application and customer master.
- Run a linkage review of your top customers by exposure, looking for shared owners, addresses, bank details, and payers.
- Create a group identifier in your system so linked accounts roll up to a single exposure figure.
- Define what counts as exposure, including open orders and unbilled shipments, and report it gross.
- Set a group limit with entity sub-limits, and document the rationale.
- Obtain guarantees where you are leaning on a parent or principal for support.
- Monitor at group level, with defined triggers for review or hold.
- Re-check linkage at every limit increase, acquisition announcement, and annual review.
- Give sales a simple way to flag "this is the same group" without needing credit team involvement.
- Review the top groups by aggregated exposure regularly with finance leadership alongside your single-name concentrations.
Common Mistakes
- Relying on customer names to detect links. Related entities frequently have unrelated names. Use identifiers and ownership data instead.
- Assuming a strong parent covers a weak subsidiary. Without a guarantee, it may not.
- Counting only invoiced balances. Open orders are exposure.
- Mapping the group once and never updating it. Acquisitions and restructurings change the picture constantly.
- Aggregating so aggressively that you lose good customers. Be clear about which link types require full aggregation and which only need review.
- Keeping group data in the credit team's head. If it is not in the system, the next sales order will ignore it.
How This Connects to Concentration Risk
Group exposure is closely related to, but not identical to, customer concentration. Concentration asks how much of your revenue or receivables depends on a few customers. Group exposure makes sure you are measuring "a customer" correctly in the first place. If you measure at account level, your concentration report can look healthy while a single group quietly accounts for a large share of your book. Fixing the unit of measurement comes first, then the concentration analysis becomes meaningful.
The Bottom Line
A credit limit is only as good as the definition of the counterparty behind it. When related entities are treated as strangers, exposure is understated, diversification is overstated, and a single group event can hit you much harder than your reports suggested.
The fix is not complicated, but it does require good data: knowing who owns and controls each buyer, linking accounts into groups, measuring exposure at group level, setting limits that reflect the real counterparty, and watching the whole structure for change. Teams that can see ownership and linkage alongside risk signals in one place find it far easier to keep group exposure under control as their customer base grows.
Ready to see the whole picture behind a buyer? Try BuyersIntelligence.ai - verify the entity, understand who controls it, and monitor the signals that matter before exposure builds up.
This article is general information about B2B credit practices and is not legal or financial advice. Insolvency law, set-off rights, and guarantee enforceability vary by jurisdiction; consult qualified counsel for your situation.
Stop guessing about buyer risk. Get instant buyer intelligence.
Try BuyersIntelligence.ai - Free →